Remortgage vs Product Transfer: Which Is Right for You?
When you buy your home you never really think about what you are going to do when your mortgage term ends. The first time we may think about sorting out our mortgage is when the bank sends us a letter telling us what our new mortgage rate will be on a ridiculously high Standard Variable Rate (SVR) for the foreseeable future, If we don't sort anything out. This is the point we start googling how to remortgage, then we go through the process of changing lender to get those better rates when sometimes, a product transfer with the same lender you were with is a better option for your circumstances. This will go through the difference between the 2 options, so you can work out which is best for you.
What is a Product Transfer?
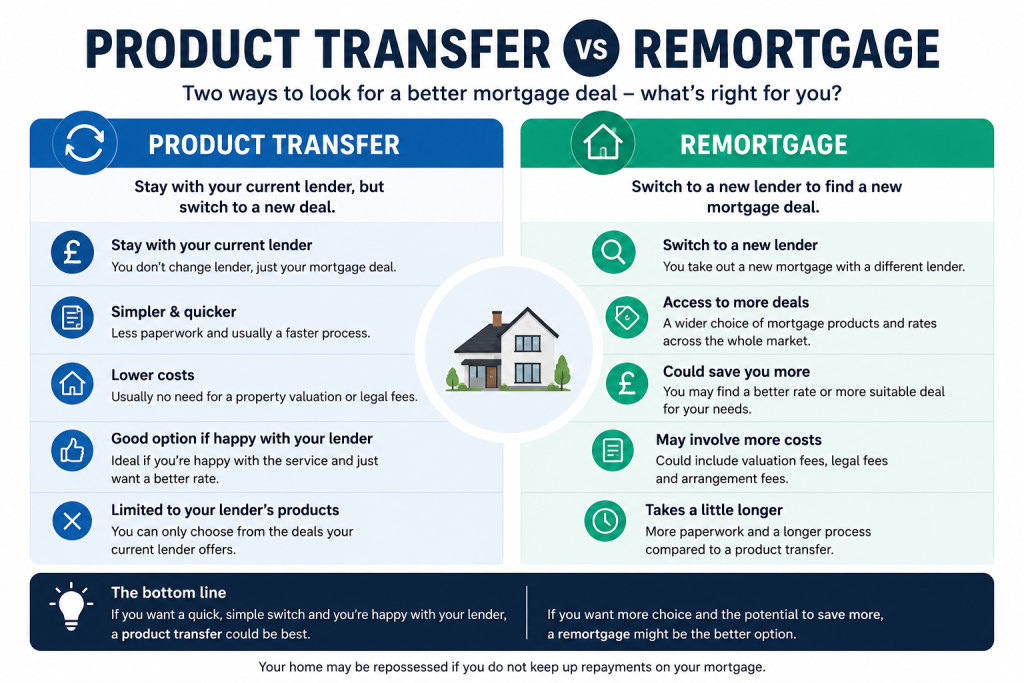
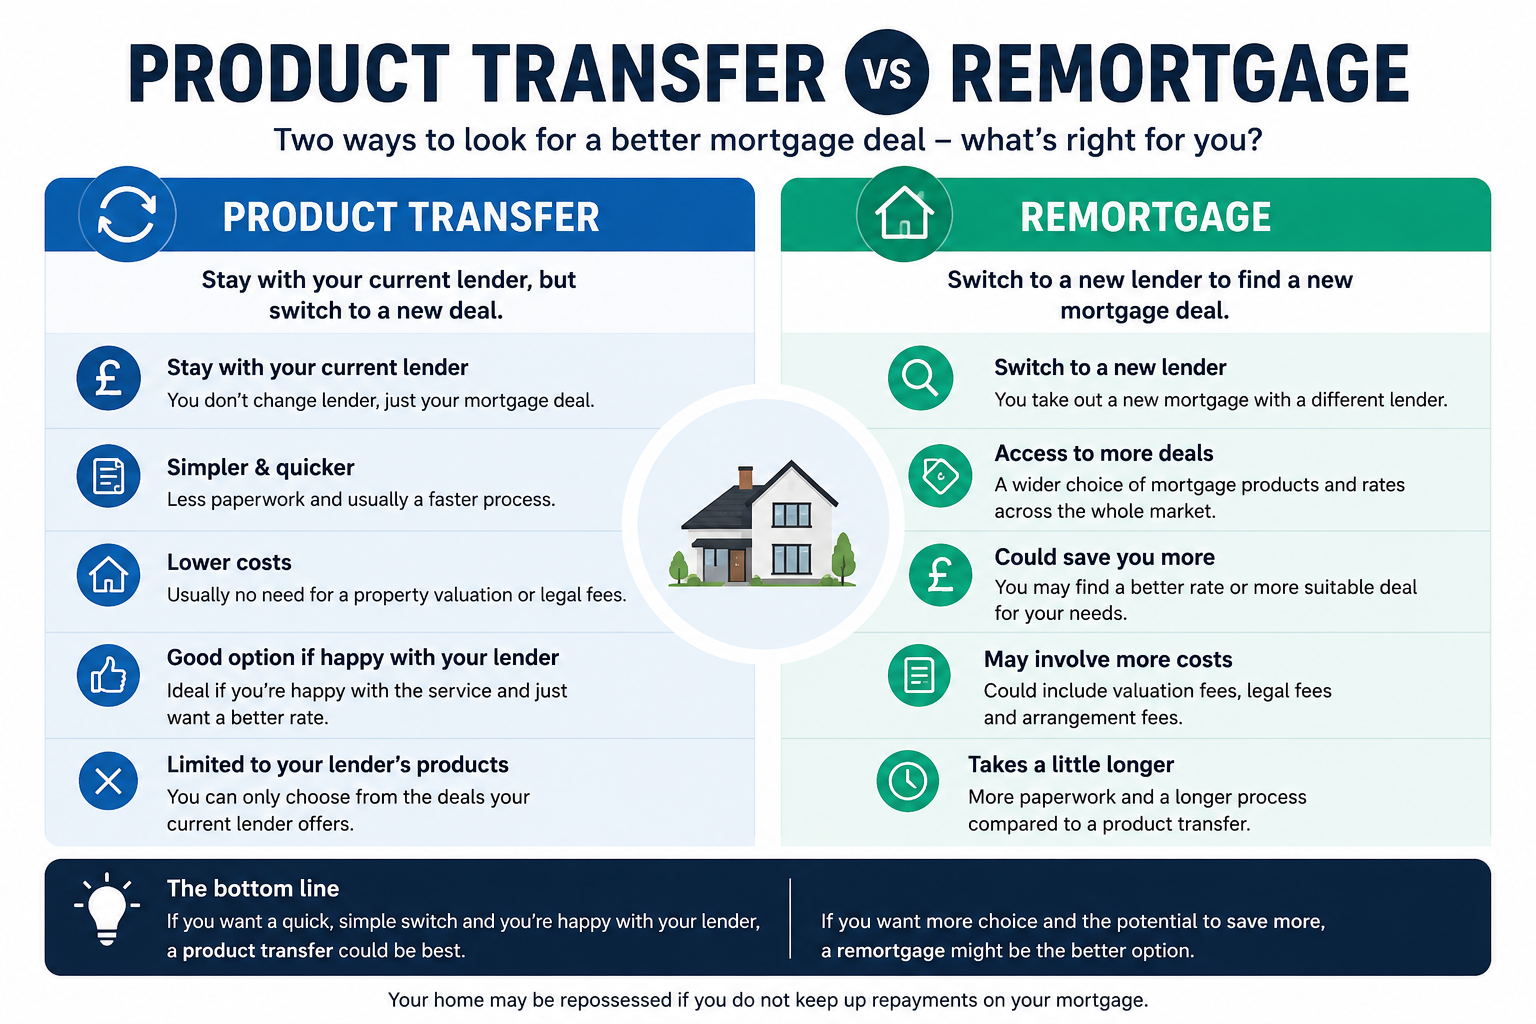
To put it simple, a product transfer is switching from your current deal onto a new deal with the same lender. For example if your mortgage is with Barclays, you move your mortgage to a different deal within Barclays. The benefits of this includes;
- Less paperwork than a remortgage as they know all your details.
- Quick. If you are running to the end of your term, this option can usually completed faster.
- Usually doesn't require a solicitor or a property valuation.
- If you have a standard mortgage and your circumstances are straightforward you should still be able to receive a competitive deal.
However you are limited to just your current lender and there could still be better deals out there for you.
What is a Remortgage?
This is where you move from one lender to another, allowing you to access a bigger variety of deals across the wider market. A remortgage would allow you to:
- Potentially secure a lower interest rate having access to the wider market. Which can lower your monthly payments.
- Change the length of your mortgage term.
- Move to a more well known lender. Sometimes our circumstances are different and for whatever reason you may have used a specialist lender to get on the housing ladder such as poor credit rate, high debt etc which potentially had higher rates. If your circumstances have improved you may now be eligible to move to a more well known lender offering better rates
- Borrow additional funds for home improvements or other purposes.
- Circumstance change. You may now be in a much better financial position and may want to find a lender that suits your current needs better with additional benefits to you.
A remortgage would usually involve a full mortgage application to be done. Including affordability checks, conveyancer costs and a valuation of the home (But some lenders do cover these costs).
Why Professional Advice Matters.
Many homeowners automatically accept the first product transfer offered by their lender because it's convenient or they aren't sure what they are doing. However, convenience and loyalty doesn't always mean the best value.
An independent mortgage adviser like us at MKS Mortgage and Protection can compare your current lender's product options alongside searching for the best remortgage deals from a wide range of lenders. This is to help you make an informed decision based on your circumstances. It is really important that we source the right mortgage for you, as a majority of homeowners do not want to be on Standard Variable Rate. One thing to remember a £200,000 mortgage over 25 years, increasing the rate from 4% to 5% raises the monthly payment by roughly £116, which is about £1400 extra per year. This is pure interest to the bank. This is why it is important to source the best mortgage that suits your needs.
Start Looking Early
By looking early it gives you time to search and compare which is the best option for you. If you do decide to do a product transfer, most lenders allow you to switch products early which can benefit you financially if a better rate than you are currently paying is on offer.
If you are going down the remortgage route to a new lender, even though you may be able to get the best deals, this takes time and paperwork needs to be gathered, and application forms filled out.
Need Help Deciding?
Whether a product transfer or a remortgage is right for you depends on your individual circumstances. We at MKS Mortgage and Protection can help you understand all of your options and potentially save you money.
If your fixed-rate mortgage is coming to an end, get in touch today for a no-obligation review. Together, we'll compare both product transfers and remortgage options to help you find the solution that's right for you.